- October 25, 2026
- Catastrophic Injury
Families who see a large verdict in the news often assume it was luck, a sympathetic jury, or a windfall. The truth is more methodical.
How large personal injury settlements are calculated comes down to a series of building blocks, each proved with evidence, and a case reaches seven figures only when every block is in place and someone has the money to pay.
Understanding those building blocks helps families judge whether a case is being valued fairly by an insurer, or even by their own legal team.
If someone you love has suffered a life-changing injury in Texas, a catastrophic injury lawyer can review the case for free and explain what its value is likely to depend on.
Key Takeaways: Seven-Figure Verdicts and Settlements in Personal Injury Cases
- Permanent injuries are valued on the cost of care and lost income over a lifetime, not on past bills.
- A life care plan and an economist translate those future needs into a present-day figure a jury can evaluate.
- Liability that reaches more than one company opens more than one insurance policy.
- Trial readiness and credibility change how insurers value the risk of a verdict.
- Texas law adds rules that can raise or limit the final figure, so each one has to be accounted for.
What makes a personal injury case worth millions?
Permanent impairment, a documented lifetime cost of care, lost earning capacity, and enough insurance or assets to pay for them.
When an injury lasts a lifetime, a Texas claim is valued on decades of future losses rather than the medical bills already incurred.
How Are Large Personal Injury Settlements Calculated?
Large settlements are calculated by adding the proven value of every category of loss, past and future, then weighing that total against the risks of trial and the insurance and assets available to pay.
The future categories usually dwarf the past ones in a catastrophic case.
Past Losses Versus Future Losses
Past losses include medical bills, lost wages, and the pain already endured.
Future losses include decades of medical care, attendant care, equipment, lost earning capacity, and the physical impairment and mental anguish a person will live with.
For a young person with a permanent brain or spinal cord injury, future losses can be many times larger than everything that came before.
Why the Same Injury Can Produce Different Values
Two people with similar injuries can have very different cases. Age, occupation, life expectancy, family responsibilities, and the strength of the liability evidence all change the result.
Asking what makes a personal injury case worth millions has no short answer, which is why no responsible lawyer can quote a value before the evidence is developed.
A Composite Case, Step by Step
The walkthrough below follows a composite catastrophic injury case, built from common patterns rather than any single client’s facts.
It shows the order in which value is built toward a seven-figure injury settlement in Texas.
- Step 1, a liability theory that reaches every responsible party: The investigation looks past the obvious defendant to every company whose decisions contributed.
- Step 2, the specialist team: Reconstructionists, engineers, treating physicians, and other specialists connect the conduct to the injury.
- Step 3, the life care plan: A qualified planner documents every future medical and support need and its cost.
- Step 4, the economist’s analysis: Future costs and lost earning capacity are projected and reduced to present value.
- Step 5, the insurance and assets available: Every policy and source of payment is identified, often under oath.
- Step 6, the settlement structure: The recovery is arranged to pay for care over the injured person’s lifetime, which makes how the settlement is structured as important as its size.
Each step depends on the one before it, and skipping any of them leaves value unproven.
A strong life care plan means little if liability cannot be proved, and a strong liability case means little if there is no insurance to pay.
Step One in Practice: Finding the Root Cause
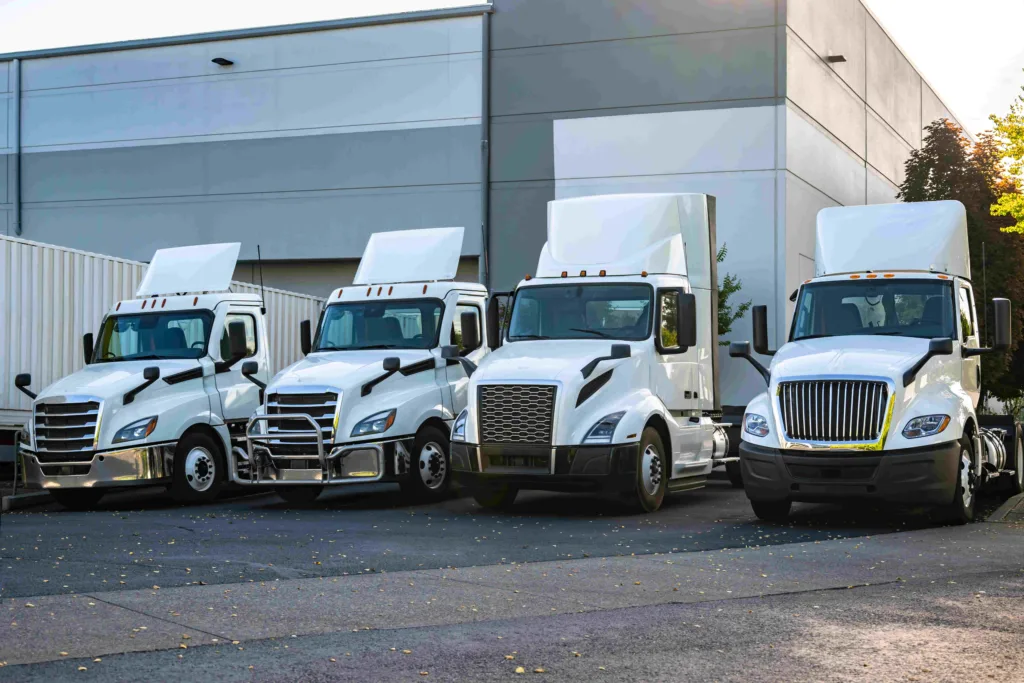
Rob Crain, a partner at Crain Brogdon, LLP, has described a case that shows how liability can expand.
A brand-new tractor-trailer lost its driveshaft on a highway, debris disabled a car, and the car’s driver was killed after getting out of the vehicle.
The investigation used metallurgists, reconstructionists, and transport specialists, and examination of the bolt heads showed the driveshaft had been removed and reinstalled.
That evidence led to the company that transported the new tractors and had its drivers reattach the driveshafts without a mechanic’s inspection. As Crain put it, the root cause was the driveshaft “falling off that truck when it never should have.”
Steps Two Through Four: Proving the Future
The specialist team and the life care plan turn a diagnosis into a detailed list of needs.
In a composite case involving a severe spinal cord injury, with or without co-occurring brain injuries, that list might include:
- Attendant care for daily tasks, priced hour by hour at local rates.
- Physician visits, therapy, medications, and supplies for life.
- Power and manual wheelchairs, replaced on a schedule.
- Home and vehicle modifications, including future updates.
- Expected complications, such as hospital stays for infections or pressure injuries.
Each item is supported by a treating physician or another qualified witness, so the plan reflects what the person will actually need rather than a wish list.
The economist then applies growth and discount rates to express those future costs in today’s dollars.
The economic proof has to follow Texas rules, including the requirement that lost earnings be presented net of federal income tax.
What Is the Final Number Built From?
[IMAGE: medical-records-folder-stethoscope.webp | alt: Medical records folder and a stethoscope on a desk]
The table below shows the main components of a catastrophic injury valuation, what each measures, and how it is usually proved.
| Component | What it measures | How it is usually proved |
|---|---|---|
| Past medical expenses | Treatment already received | Bills and records, limited to amounts actually paid or incurred |
| Future medical and attendant care | Care needed for the rest of the person’s life | Life care plan, treating physicians |
| Lost earnings and earning capacity | Income lost now and in the future | Employment records, vocational testimony, economist |
| Physical impairment | Loss of the body’s function | Medical testimony, family and coworker accounts |
| Pain and mental anguish | Suffering past and future | Testimony from the injured person and those close to them |
| Disfigurement | Visible, lasting changes | Photographs, medical testimony |
| Exemplary damages | Punishment for gross negligence or malice | Evidence of the defendant’s conscious disregard of risk |
Non-economic categories like impairment and mental anguish are decided by the jury based on the evidence, with no formula.
In catastrophic cases, these categories often carry great weight because the jury hears how completely a person’s life has changed.
Texas Rules That Shape the Final Figure
Texas law includes several rules that can raise, reduce, or cap parts of a recovery. A realistic valuation accounts for each of them:
- Paid or incurred medical expenses: Recovery for past medical costs is limited to amounts actually paid or incurred, which can be less than the billed amount. The same chapter caps exemplary damages in most cases.
- Proportionate responsibility: Under Chapter 33, any fault assigned to the injured person reduces the recovery, and fault above 50 percent bars it.
- Government defendants: Claims against government entities are subject to strict notice rules and damage caps.
- Commercial vehicle trials: In cases involving commercial motor vehicles, Texas law lets the defendant request a bifurcated trial that separates certain liability and damages questions.
There is no general cap on compensatory damages in an ordinary negligence case in Texas.
That is one reason careful proof of future losses matters so much.
Insurance Layers
A single auto policy may carry limits far below the cost of a catastrophic injury.
Commercial defendants often have primary policies, excess policies, and umbrella coverage stacked on top of each other, and federal rules require interstate trucking companies to carry minimum levels of financial responsibility.
Each additional responsible party may bring its own layers. Our trucking guide explains how insurance layers affect claim value.
Why Do Some Injury Cases Settle for More?
[IMAGE: empty-conference-room-mediation.webp | alt: Empty conference room set for a mediation]
Insurers value cases based on what they expect a jury to do and how confident they are in the other side’s preparation.
Several factors move that estimate.
Finding All the Insurance
Rob Crain has described how often coverage turns out to be larger than first reported: “And we don’t take that answer until we get somebody under oath.”
Discovery, depositions, and careful review of contracts can reveal excess policies and additional insured parties that were not disclosed at first.
Resources to See the Case Through
Catastrophic cases are expensive to prepare. “We have cases that are closer to a million dollars in expenses than they are to zero,” Rob Crain has said of the firm’s work.
A firm that can fund reconstructions, models, and the expert team a catastrophic case requires puts pressure on an insurer that hopes the case will settle cheaply.
Credibility and Trial Readiness
Insurers know which lawyers are prepared to try a case to a catastrophic injury verdict in Texas and which are not.
A case built honestly, with its weaknesses addressed rather than hidden, carries more value because the defense knows it can hold up before a jury.
Mediators and judges notice the same thing, and that credibility often shapes the final stages of negotiation.
Results That Reflect This Approach
Crain Brogdon, LLP has recovered more than $355 million in verdicts and settlements, including a $142,000,000 verdict in a fatal child care negligence case, a recovery of $8,125,169, and a commercial-truck jury award of just over $6,000,000.
More examples appear in our case results.
Past results do not predict or promise the outcome of any future case, and every case depends on its own facts.
FAQs: How Large Personal Injury Settlements Are Calculated
How long does a seven-figure injury case take in Texas?
Often two years or more. Catastrophic cases in Texas usually cannot be valued until the injured person’s condition stabilizes, and complex liability investigations, specialist reports, and depositions take time.
Cases that go to trial can take longer, and appeals can add more time after a verdict.
Can I change lawyers if I think my Texas case is being undervalued?
Yes. A client in Texas can change lawyers during a case, and fee arrangements between the old and new firms are typically worked out so the client does not pay two full fees.
A second opinion before accepting a settlement can be especially valuable when the injury is permanent.
Do large verdicts get reduced after trial in Texas?
Sometimes. In Texas, a judge can apply statutory caps, such as the limit on exemplary damages, and reduce medical expenses to amounts actually paid or incurred.
Either side can also appeal, which can change or delay the final amount.
Who pays the costs of building a catastrophic injury case?
In most Texas catastrophic injury cases handled on a contingency fee, the law firm advances the costs of investigation, specialists, and litigation.
Those costs are typically repaid from the recovery, as described in the fee agreement, and families usually pay nothing if there is no recovery.
Are large personal injury settlements taxed in Texas?
Compensatory damages for a physical injury are generally not taxed as income under federal law, and Texas has no state income tax.
Exemplary damages and interest are treated differently, so a tax professional should review any large Texas settlement that includes them.
Answers About What Your Case Is Really Worth
A seven-figure case is not built on luck.
It is built on finding the truth about what happened, proving what the injury will cost over a lifetime, and holding every responsible party accountable.
Crain Brogdon, LLP represents families across Texas in catastrophic injury and wrongful death cases, with a focus on answers and accountability.
Call (214) 522-9404 for a free, confidential consultation about your family’s case.
Attorney Quentin Brogdon
Quentin Brogdon has over thirty years of experience and expertise in the field of personal injury trial law. He is board certified in both personal injury trial law and civil trial advocacy. Quentin has received an AV rating from Martindale-Hubbell, the highest possible rating. This rating reflects an attorney’s ethics and abilities according to reviews from fellow attorneys. [ Attorney Bio ]

Recent Comments