- October 9, 2026
- Catastrophic Injury
Agreeing on what a case is worth is only half of the settlement decision.
The other half is how the money will be paid, and for someone with a permanent injury, the choice between a structured settlement vs lump sum can matter as much as the final number.
A payment plan that runs out too soon, or one that cannot adapt to a family’s needs, can undo years of work on the case itself.
This decision usually has to be made before the settlement is final, and it is difficult to reverse. If your family is weighing these options after a catastrophic injury, a Texas catastrophic injury lawyer can review your situation for free and explain how each choice would work.
Key Takeaways: Structured Settlement vs. Lump Sum
- A structured settlement pays all or part of a recovery over time, usually through an annuity purchased at the time of settlement.
- A lump sum pays the full amount at once and gives the recipient complete control over how it is used.
- Compensatory damages for a physical injury are generally not taxable as income, whether paid in a lump sum or in periodic payments.
- Many catastrophic injury settlements combine the two, with a cash portion for immediate needs and a structure for long-term care.
- Once a structured settlement is set up, its payment schedule is generally fixed and cannot be easily changed.
Is a structured settlement better than a lump sum?
It depends on the injured person’s needs.
A structured settlement usually suits someone with a permanent injury who needs lifetime income or relies on needs-based benefits, while a lump sum offers immediate access and control but can be spent down.
Should I Take a Structured Settlement or a Lump Sum?
If the injury is permanent and the injured person relies on needs-based benefits, a structured settlement usually offers more protection.
A lump sum offers control and flexibility, but it requires discipline and careful investing to last a lifetime.
Neither choice is right for every family. The answer depends on the injured person’s age, life expectancy, care needs, other income, and comfort with managing a large sum of money.
What Each Option Means in Practice
A structured settlement in a Texas personal injury case works like a scheduled paycheck that does not depend on the stock market.
The defendant or its insurer funds the annuity behind the personal injury settlement, and the annuity company makes payments on a schedule set at the time of settlement, such as monthly for life, with larger payments at specific ages.
A lump sum is a single payment.
After fees, expenses, and liens are paid, the remaining money belongs to the injured person, who can invest it, spend it, or place it in a trust.
Structured Settlement vs Lump Sum: A Side-by-Side Comparison
The table below compares the two approaches on the factors families most often ask about.
| Factor | Structured settlement | Lump sum |
|---|---|---|
| Access to money | Paid on a fixed schedule | Available immediately |
| Flexibility | Very limited once set up | Complete |
| Investment growth | Growth built into the annuity is generally not taxed | Investment earnings are generally taxable |
| Protection against overspending | Strong, because future payments cannot be spent early | Depends entirely on the recipient’s choices |
| Inflation | Can include annual increases if chosen at the outset | Depends on how the money is invested |
| Effect on needs-based benefits | Payments can count as income unless directed to a trust | Lump sum can count as a resource unless placed in a trust |
| Risk | Depends on the financial strength of the annuity company | Depends on investment performance and spending |
| Changing course later | Selling payments requires court approval and usually costs money | No restrictions |
These factors pull in different directions for different families.
A young person with lifelong care needs and a parent with significant savings may reach opposite conclusions.
Why Taxes Favor Structured Payments for Many Families
Are personal injury settlements taxable in Texas? Under federal tax law, compensatory damages received on account of a personal physical injury are generally excluded from income, whether they are received as a lump sum or as periodic payments.
That exclusion is the starting point for both options.
Where the Difference Appears
The difference shows up in growth over time. When a lump sum is invested, the earnings on those investments are generally taxable.
When an annuity funds a qualified structured settlement, the full periodic payments, including the growth built into the annuity, are generally treated as tax-free damages.
Qualified Assignments
Most structured settlements use a qualified assignment, in which the defendant’s obligation to make future payments is transferred to an assignment company that buys an annuity.
The rules for these arrangements appear in Section 130 of the Internal Revenue Code.
A tax professional should review any settlement that includes punitive damages or interest, which are treated differently.
Protecting Benefits for Clients Who Will Never Work Again
Many catastrophic injury clients, including families with traumatic brain injury claims, rely on Medicaid for long-term care or on Supplemental Security Income (SSI).
Both programs consider what a person owns and receives, and the Social Security Administration counts most income when deciding SSI eligibility and payment amounts.
Directing Payments to a Trust
Either a lump sum or structured payments can affect eligibility if paid directly to the injured person.
A common solution is to direct the money into a properly drafted special needs trust, which can pay for care and quality-of-life needs without counting against benefit limits. Structured payments can be made payable to the trust for years into the future.
Our guide to guardianships and special needs trusts explains how courts approve these arrangements.
Coordinating With Planners
These benefit rules are technical, and mistakes can cost a family coverage it depends on.
Coordinating with a special needs planner before the settlement is finalized allows the structure, the trust, and the benefits to work together.
What Mistakes Do Families Make With Settlement Payments?
The settlement payment decision comes at a stressful moment, often after years of litigation. A few mistakes come up again and again:
- Deciding without a life care plan: Without a clear picture of future costs, it is impossible to know whether a payment schedule will keep up with care needs.
- Taking all cash to pay off every debt at once: Paying debts can make sense, but spending most of a recovery in the first year leaves little for care decades from now.
- Structuring too much: Locking every dollar into fixed payments can leave a family unable to buy a home, a vehicle, or equipment when it is needed.
- Ignoring benefits: Receiving money directly, instead of through a trust, can end Medicaid or SSI eligibility a person depends on.
- Skipping inflation protection: A monthly payment that looks generous today may cover far less in 20 years.
Why the Timing Matters
Most of these mistakes happen because the payment decision is rushed at the end of a case.
Knowing how long a settlement takes helps families plan ahead.
Starting the conversation months before settlement, with the life care planner and a structured settlement consultant involved, gives the family time to compare real proposals rather than rough estimates.
Questions to Ask Before Choosing
Anyone asking whether they should take a lump sum settlement should start with an honest look at the family’s needs. These questions help organize that conversation:
- What will the injured person’s care cost each year, according to the life care plan?
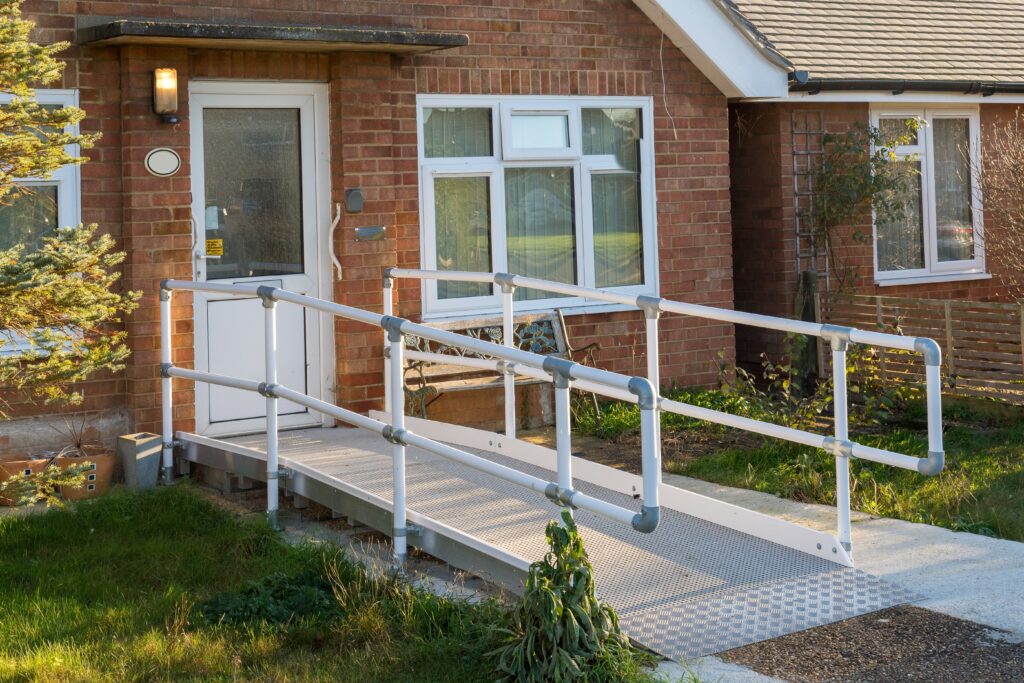
- Are there large near-term expenses, such as a wheelchair-accessible home or vehicle?
- Does the injured person receive, or expect to need, Medicaid or SSI?
- Who will manage the money, and how comfortable are they with investing?
- Are there other sources of income, such as a spouse’s job or disability insurance?
- How important is the ability to change plans later?
The answers often point to a combination.
A family might take enough cash to cover immediate needs and fund a home modification, then structure the rest to pay for care over the injured person’s lifetime.
What If a Family Wants to Sell Structured Payments Later?
Companies frequently advertise cash now for structured settlement payments. Texas law limits these sales to protect injured people.
Under the Texas Structured Settlement Protection Act, a transfer of structured settlement payment rights generally requires court approval.
The court must find that the transfer serves the payee’s interest, considering the welfare of any dependents, and the buyer must provide required disclosures about the amounts involved.
Even when a sale is approved, the price is usually far less than the total of the future payments given up.
Why This Matters at the Start
Because changing course later is expensive, the structure should be designed carefully at the outset.
Building in some flexibility, such as periodic lump sums at planned intervals, can reduce the temptation to sell payments when a large expense appears.
How Our Firm Approaches This Decision
Crain Brogdon, LLP handles catastrophic injury cases, and our clients, including those with spinal cord injury claims, often face exactly this choice.
We work through the life care plan, the family’s needs, and the benefits picture before settlement so the payment structure supports the injured person for the long term.
Bringing the Right Advisers In
We work alongside structured settlement consultants, financial planners, and special needs planners, who help design the specific annuity and trust arrangements.
Their proposals are reviewed against the life care plan, so the family can see how each option would pay for care in the years ahead before anything is signed.
FAQs: Structured Settlements in Texas Injury Cases
Can I choose a structured settlement after I have already received a lump sum?
Generally, no. For the tax benefits of a qualified structured settlement, the structure must be agreed to as part of the settlement before the injured person receives the money.
Once a Texas injury settlement is paid as cash, that money can be invested, but it cannot be converted into a qualified structure.
What happens to structured settlement payments if the injured person dies?
It depends on how the structure was set up. In Texas injury settlements, families can choose payments that continue to named beneficiaries for a set minimum period, or payments for life only, which usually provide more income per month.
The choice should match the family’s priorities and the injured person’s health.
Who pays the attorney’s fees in a structured settlement?
Fees and case expenses are usually paid from the cash portion of the settlement at the time it is finalized. In Texas, some arrangements also allow the attorney’s fee itself to be structured, but that is a separate agreement.
The settlement documents should show exactly how fees, expenses, and liens are handled.
Is a structured settlement safe if the annuity company has financial problems?
The risk is generally low, but it is not zero. Annuities used for structured settlements are typically issued by large life insurance companies, and state guaranty associations, including in Texas, provide some protection up to statutory limits.
Families with very large structures sometimes spread the payments across more than one annuity company.
Can a structured settlement include payments that increase over time?
Yes. A structure can include annual cost-of-living increases or larger payments at future dates, such as when a child starts college or when expected surgeries occur.
These features are set at the time of the Texas settlement and generally cannot be added later.
Making the Choice That Protects the Future
How a settlement is paid can determine whether it still covers care decades from now.
Taking time to understand the trade-offs, with the life care plan and the family’s real needs in view, leads to decisions families can live with.
Crain Brogdon, LLP represents catastrophic injury clients across Texas and helps families plan how a recovery will be paid, not only how much it will be.
Call (214) 522-9404 for a free, confidential consultation.
Attorney Quentin Brogdon
Quentin Brogdon has over thirty years of experience and expertise in the field of personal injury trial law. He is board certified in both personal injury trial law and civil trial advocacy. Quentin has received an AV rating from Martindale-Hubbell, the highest possible rating. This rating reflects an attorney’s ethics and abilities according to reviews from fellow attorneys. [ Attorney Bio ]

Recent Comments